
Territory specific provisions
Schedule 2 Territory specific provisions
sections
8 and 100
Part 1 Introduction to
Schedule
1 Application of Schedule
This Schedule sets out provisions that apply only in this jurisdiction.
2 Definitions
In this Schedule:
baseline count, see clause 20A.
financial year means the financial year commencing on
1 July 2009 or on 1 July in any subsequent financial year.
group threshold amount, see clause 8 of Schedule 1.
resident employee, see clause 20A.
Part 2 Calculation of monthly payroll tax
Division 2 Employers who are not members of a group
4 Application of Division
This Division applies only to an employer who is not a member of a group.
5 Amount of payroll tax to be paid each month
The amount of payroll tax payable by an employer on taxable wages paid or payable by the employer in a month is the amount of dollars calculated in accordance with the following formula:
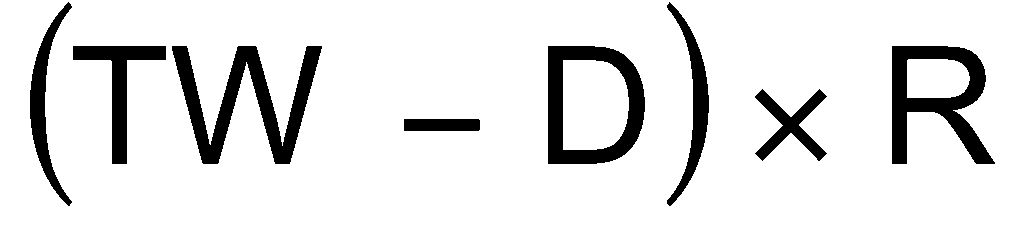
where:
TW is the total taxable wages paid or payable by the employer (otherwise than as a member of a group) during the month.
D is the deductible amount mentioned in clause 6 or 7 (as the case requires).
R is the rate of payroll tax applicable under section
7A.
If D is equal to or more than TW in respect of a month, the employer is not required to pay payroll tax in respect of that month.
6 Deductible amount for employer who does not pay interstate wages
For an employer who pays or is liable to pay taxable wages in a month but does not pay and is not liable to pay interstate wages in that month, the deductible amount in respect of that month is an amount not exceeding the amount in dollars calculated in accordance with the following formula, as determined in a manner approved by the
Commissioner:
TA
12
where:
TA is the threshold amount for the financial year as defined in Schedule 1, clause 1.
Subclause (1) applies whether the employer pays or is liable to pay wages for the whole of the month or only part of the month.
7 Deductible amount for employer who pays interstate wages
The deductible amount for an employer who pays or is liable to pay taxable wages and interstate wages in a month is an amount determined in a manner approved by the Commissioner.
The deductible amount claimed cannot be more than the amount mentioned in clause 6(1).
Division 3 Groups with designated group employer
8 Application of Division
This Division applies only to an employer who is a member of a group of which there is a designated group employer.
9 Amount of payroll tax to be paid each month
If an approval is in force under section 87(2) for the designated group employer to lodge a joint return:
the amount of payroll tax payable by the designated group employer on taxable wages paid or payable in a month by the employers covered by the return is the amount of dollars calculated in accordance with the following formula:
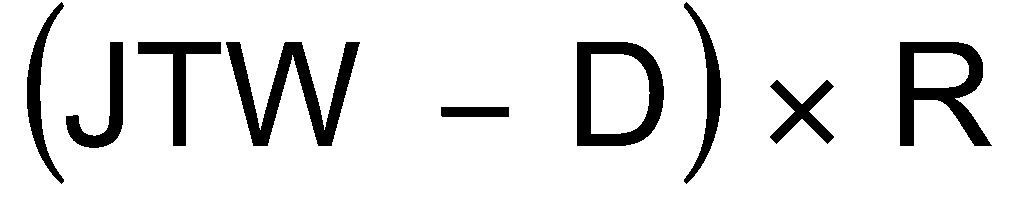
where:
JTW is the total taxable wages paid or payable during the month by the employers covered by the return (as members of a group).
D is the deductible amount mentioned in clause 10 or 11 (as the case requires).
R is the rate of payroll tax applicable under section
7A; and
the amount of payroll tax payable by each employer who is a member of the group but is not covered by the return on taxable wages paid or payable by the employer in a month is the amount of dollars calculated in accordance with the following formula:
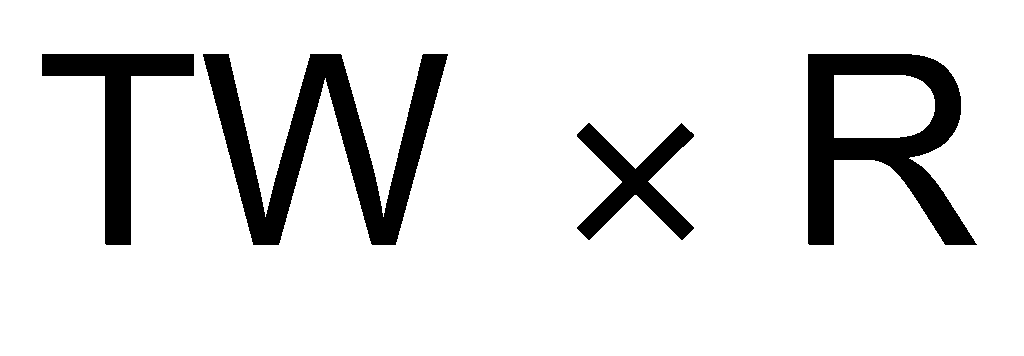
where:
TW is the total taxable wages paid or payable by the employer concerned (as a member of the group) during the relevant month.
R is the rate of payroll tax applicable under section 7A.
If an approval under section 87(2) is not in force for the designated group employer:
the amount of payroll tax payable by the designated group employer on taxable wages paid or payable by the designated group employer in a month is the amount of dollars calculated in accordance with the following formula:
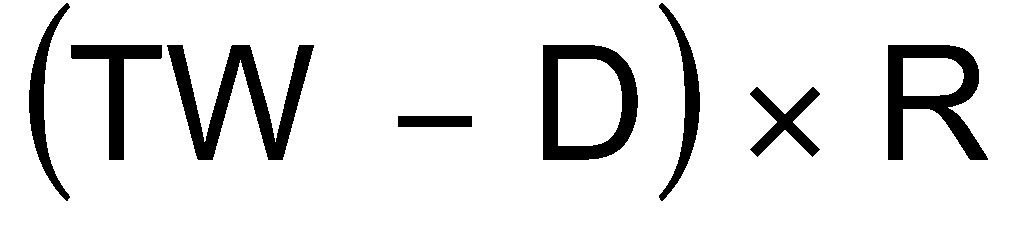
where:
TW is the total taxable wages paid or payable by the designated group employer (as a member of a group) during the month.
D is the deductible amount mentioned in clause
10 or 11 (as the case requires).
R is the rate of payroll tax applicable under section 7A; and
the amount of payroll tax payable by each employer who is a member of the group on taxable wages paid or payable by the employer in a month is the amount of dollars calculated in accordance with the following formula:
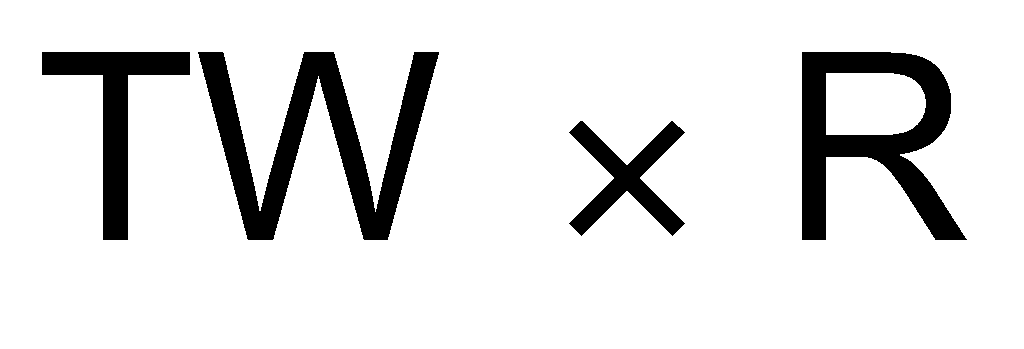
where:
TW is the total taxable wages paid or payable by the employer concerned (as a member of the group) during the relevant month.
R is the rate of payroll tax applicable under section 7A.
For subclauses (1)(a) and (2)(a), if D is equal to or more than
JTW or TW in respect of a month (as the case requires), the designated group employer is not required to pay payroll tax in respect of that month.
10 Deductible amount for groups that do not pay interstate wages
For a group in which 1 or more members pay or are liable to pay taxable wages in a month but no members pay or are liable to pay interstate wages in that month, the deductible amount in respect of that month is an amount not exceeding the amount in dollars calculated in accordance with the following formula, as determined in a manner approved by the Commissioner:
TA
12
where:
TA is the threshold amount for the financial year as defined in Schedule 1, clause 1.
Subclause (1) applies whether group members pay or are liable to pay wages for the whole of the month or only part of the month.
11 Deductible amount for groups that pay interstate wages
The deductible amount for a group in which 1 or more members pay or are liable to pay taxable wages or interstate wages in a month is an amount determined in a manner approved by the Commissioner.
The deductible amount claimed cannot be more than the amount mentioned in clause 10(1).
Division 4 Groups with no designated group employer
12 Application of Division
This Division applies only to an employer who is a member of a group of which there is no designated group employer.
13 Amount of payroll tax to be paid each month
The amount of payroll tax payable by each member of the group on taxable wages paid or payable by the member in a month is the amount of dollars calculated in accordance with the following formula:
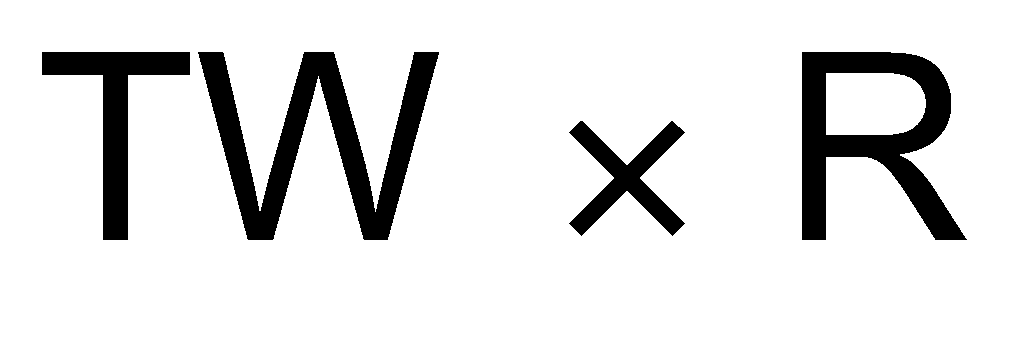
where:
TW is the total taxable wages paid or payable by the employer concerned (as a member of the group) during the relevant month.
R is the rate of tax payroll tax applicable under section 7A .
Part 3 Payroll tax for financial year
14 Payroll tax for financial year for group that has designated group employer
This clause applies to a group if:
there is a designated group employer of the group; and
the total taxable wages and interstate wages paid or payable by the group during the financial year is more than the group threshold amount; and
clause 9 of Schedule 1 does not apply to the group.
The designated group employer of the group is liable to pay as payroll tax for the financial year the amount of dollars calculated in accordance with the following formula:
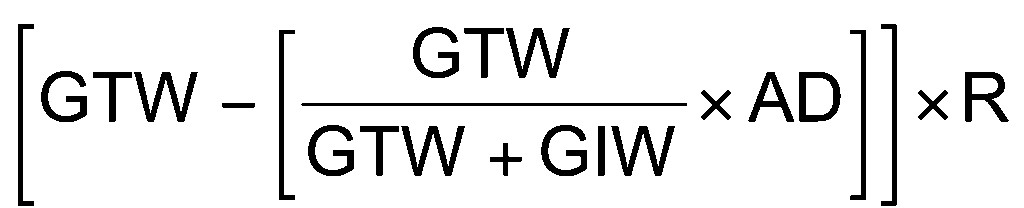
In this clause:
AD or annual deduction means the following:
if the amount worked out in accordance with the formula set out in paragraph (b) is zero or a negative amount – zero;
otherwise – the amount worked out in accordance with the following formula:
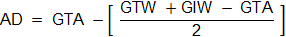
GIW is the total interstate wages paid or payable by the members of the group during the relevant financial year.
GTA, see Schedule 1, clause 8.
GTW is the total taxable wages paid or payable by the members of the group during the relevant financial year.
R is the rate of payroll tax applicable under section
7A.
Note for clause 14
For the calculation of the payroll tax payable for a financial year by an employer who is a member of a group of which there is no designated group employer, see clause 12 of Schedule 1.
15 Adjustment of payroll tax for group
If an amount of payroll tax paid for a financial year in respect of a group is greater than the correct amount of payroll tax payable in respect of the financial year for the group, the Commissioner (on application by a member of the group) is to refund the amount equal to the difference to the designated group employer of the group or, if the Commissioner considers it appropriate, another member of the group.
If an amount of payroll tax paid for a financial year in respect of a group is less than the correct amount of payroll tax payable in respect of the financial year for the group, the designated group employer of the group or, if the Commissioner considers it appropriate, another member of the group, must pay the Commissioner as payroll tax an amount equal to the difference.
Part 4 Exemptions
Division 1 Education and training
16 Schools and colleges
Wages are exempt wages if they are paid or payable by a school or college (other than a technical school or a technical college) that:
provides education at or below, but not above, the secondary level of education; and
is carried on by a body corporate, society or association otherwise than for the purpose of profit or gain to the individual members of the body corporate, society or association and is not carried on by or on behalf of the Territory.
17 Apprentices and trainees
Wages are exempt wages if they are paid or payable to an employee who is an apprentice or trainee.
Despite subsection (1), wages paid or payable to a trainee by an employer are not exempt wages if, immediately before the commencement of the trainee's traineeship with the employer, the trainee had been employed by the employer for a continuous period of:
for a full-time employee – 3 months or more; or
for a part-time or casual employee – 12 months or more.
In this clause:
apprentice, see section 5 of the Training and Skills
Development Act 2016.
trainee, see section 6 of the Training and Skills
Development Act 2016.
Division 2 Health care service providers
19 What is a health care service provider
For Part 4, Division 3 of this Act, a health care service provider is:
a public hospital; or
a hospital that is carried on by a society or association otherwise than for the profit or gain to the individual members of the society or association.
Division 3 Paternity leave
20 Paternity leave
Wages are exempt wages if they are paid or payable to an employee in respect of leave (paternity leave):
given to a male employee in connection with:
the pregnancy of a female carrying his unborn child; or
the birth of his child; and
that is not sick leave, recreation leave, annual leave or any similar leave.
For subclause (1), it is immaterial whether the leave is taken during or after the pregnancy.
The exemption is limited to wages paid or payable in respect of a maximum of 14 weeks paternity leave given to an employee in respect of any one pregnancy.
In subclause (3):
a reference to 14 weeks paternity leave includes a reference to an equivalent period of leave at a reduced rate of pay; and
a reference to wages paid or payable in respect of a period of leave is a reference to the total wages that would normally have been paid or payable for that period of leave.
Example for subclause (4)
For a part-time employee, the exemption may apply to wages paid or payable for paternity leave that extends to 28 weeks at half of the part-time rate of pay that would normally apply to the employee.
The exemption does not apply to any part of wages paid or payable in respect of paternity leave that comprises fringe benefits.
An employer wishing to claim an exemption in respect of paternity leave given to an employee must obtain and keep a statutory declaration by the employee stating that:
a female is or was pregnant with the employee's unborn child; or
the employee's child has been born and the date of the birth.
Note for subclause (6)
Section 79 of the Taxation
Administration Act 2007 requires these records to be kept for at least 5 years unless the Commissioner authorises earlier destruction.
Division 4 Hiring resident employees
20A Definitions
In this Division:
baseline count, in respect of an employer, means the total number of resident employees employed by the employer on
30 April 2018.
resident employee means an employee whose principal place of residence is in the Territory.
20B Relocating or replacing employees with resident employees on or after 1 May 2018
Wages are exempt wages if:
the wages are paid or payable to a resident employee; and
the resident employee was an employee of the employer on 30 April
2018; and
the resident employee formerly resided outside the Territory but relocated to a principal place of residence in the Territory on or after 1 May 2018 and before 1 July 2021.
Example for subclause (1)
A fly-in fly-out employee relocates to the Territory on 1 September 2018. The employer can claim the exemption, regardless of the baseline count.
Wages are exempt wages if:
the wages are paid or payable to a resident employee; and
the resident employee was hired on or after 1 May 2018 and before 1 July 2021; and
the resident employee was hired to replace a former employee whose principal place of residence was outside the Territory; and
the former employee was an employee of the employer on 30 April
2018; and
the replacement occurred within 6 months of when the former employee ceased to be an employee.
Example for subclause (2)
A fly-in fly-out employee, hired before 1 May 2018, ceases to be employed. The position is filled within 6 months by a new employee who lives in the
Territory. The employer can claim an exemption, regardless of the baseline count.
20C Hiring new resident employees on or after 1 May 2018
Wages are exempt wages if:
the wages are paid or payable to a resident employee; and
the resident employee was hired on or after 1 May 2018 and before 1 July 2021.
The number of resident employees for which the exemption under subclause (1) is available in a month is limited to the number of resident employees, calculated on the last day of the month, that exceeds the baseline count, less the number of any resident employees mentioned in clause 20B.
Example for clause 20C
An employer had 50 resident employees on 30 April 2018 (baseline count). None of the resident employees were of the kind mentioned in clause 20B. In May 2018,
3 resident employees resigned and were replaced by 4 more resident employees. Under this clause the exemption is only available for 1 of those 4 resident employees.
20D Other conditions
The exemptions under this Division are available only in respect of wages paid or payable during the 2-year period beginning on the date the resident employee's wages first became eligible for the exemption.
Example for subclause (1)
If a resident employee is hired on 1 September 2018 and the wages are eligible for the exemption, the exemption is available only until 31 August 2020.
The exemptions under this Division apply in relation to:
a full-time employee; and
a part-time employee; and
a person taken to be an employee under Part 3, Division 7 of this Act.
The exemptions under this Division do not apply in relation to:
a casual employee; or
a person taken to be an employee under Part 3, Division 8 of this Act.
20E Record keeping
An employer wishing to claim an exemption under this Division must obtain and keep sufficient records to satisfy the requirements for the claim.
Note for clause 20E
Section 79 of the
Taxation Administration Act 2007 requires these records to be kept for at least 5 years unless the Commissioner authorises earlier destruction.
20F Power to vary or refuse
The Commissioner may make an order under subclause (2) if satisfied that:
despite the appearance of an increase in the number of resident employees after 30 April 2018, in substance, no material change in that number occurred; or
the claim, the baseline count or other information on which a claim is made is not based on an accurate reflection of the employer's situation or the circumstance of the employer's employees;
or
the claim is not justified by any material benefit to the employment of resident employees; or
the structure of the employer's business has significantly changed since 30 April 2018.
The Commissioner may, by order:
vary or refuse, in whole or in part, a claim for the exemption;
or
vary the baseline count for an employer, or allocate baseline counts among employers.
20G Guidelines
The Commissioner may issue written guidelines about exemptions and other matters under this Division.
A guideline may be of general or specific application.
A claim for an exemption is taken to be a valid claim to the extent that it complies with the guidelines in force under this clause.
A guideline does not affect:
the exercise by the Commissioner of a power under this Act; or
the right of a person to have the Commissioner exercise a power under this Act.
Part 5 Government bodies –
special provisions
21 Application of Act to Government Business Divisions and statutory corporations
A Government Business Division is taken to be an employer for this Act.
A Government Business Division or statutory corporation (rather than the Commissioner for Public Employment) will be regarded for this Act as the employer of all employees assigned to work in it.
If a Government Business Division is not a corporation, this Act applies to it as if it were a corporation.
In this clause:
Government Business Division means an Agency or a part of an Agency that:
is a Government Business Division as defined in section 3(1) of the Financial Management Act 1995; and
is not excluded by regulation from the operation of this clause.
This Act’s bill:Explanatory statementSecond reading speech
The statute text is free to read above. View subscription options to unlock the case-law research tools for each provision.