
Calculation of duty
102A Calculation of duty
The duty in respect of a transaction under which a person or group acquires a prescribed interest in a land holding entity is to be equivalent to—
in the case of an entity that is a private company or a private unit trust—the duty payable on a conveyance of land with an unencumbered value equivalent to the value of the acquirer's notional interest in the entity's underlying local land assets; and
in the case of an entity that is a listed company or a public unit trust scheme—10% of the duty payable on a conveyance of land with an unencumbered value equivalent to the value of the acquirer's notional interest in the entity's underlying local land assets.
Duty on a dutiable transaction under which a person or group increases its prescribed interest in a land holding entity is to be calculated as follows:
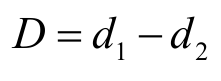
Where—
D is the amount of the duty
d1 is the amount that would have been payable if the person or group had acquired the whole of its interest in a single transaction at the time of the increase
d2 is the amount that would have been payable if the person or group had acquired its pre-existing interest in a single transaction at the time of the increase.
If—
a person or group holds an interest in a relevant entity; and
the relevant entity then acquires land so as to become a land holding entity; and
the acquisition under paragraph (b) was subject to ad valorem duty that has been duly paid; and
the person or group acquires a prescribed interest in the entity as a land holding entity, the duty calculated under subsection (1) is to be reduced in accordance with the following formula:
Where—
D is the amount of the duty to be paid on account of this subsection
d1 is the amount that would have been payable if the person or group had acquired the whole of its interest in a single transaction at the time of the acquisition
d2 is the amount that would be payable on a conveyance of an interest in the relevant land corresponding to the interest held by the person or group at the time of the acquisition under paragraph (b)
relevant land is the total amount of land in South Australia that is held by the land holding entity at the time that the person or group acquires the prescribed interest under paragraph (d).
If any part of a prescribed interest in a land holding entity was acquired by the relevant person or group more than 3 years before the date of a dutiable transaction (the earlier acquisition), the duty calculated under subsection (1) is to be rebated by a percentage representing the extent of the earlier acquisition as a proportion of the prescribed interest as a whole.
Insofar as subsections (4) and (5) may both apply to the acquisition of a prescribed interest in a particular land holding entity by a person or group, the provision that provides the higher benefit to the person or group will apply.
If a person or group acquires or increases a prescribed interest in a land holding entity and duty has been paid under this Act in respect of the transaction for the acquisition of, or increase in, the interest, the duty calculated under this section is to be reduced by the amount of duty paid under this Act.
The statute text is free to read above. View subscription options to unlock the case-law research tools for each provision.