
Concessional duty to encourage exploration activity
71D Concessional duty to encourage exploration activity
Where upon an application made under this section the Treasurer, after consultation with the Minister to whom the administration of the
Mining
Act 1971 is committed, is satisfied—
that the applicants are parties to a conveyance of a prescribed tenement or an interest in a prescribed tenement; and
that the consideration or a part of the consideration for the conveyance consists of an undertaking on the part of the person or persons acquiring an interest in the tenement by virtue of the conveyance—
to engage in exploratory or investigatory operations (to be carried on after the date of the undertaking) within that part of the area of the tenement to which the conveyance relates; or
to contribute to the cost of exploratory or investigatory operations (to be carried on after the date of the undertaking) within that
part of the area of the tenement to which the conveyance relates, this section applies to the conveyance.
An application under this section must—
be made in a manner and form determined by the Treasurer; and
set out a statement of—
the value of the interest being transferred by the conveyance; and
the value of the undertaking referred to in subsection (1)(b);
and
be accompanied by such evidence as the Treasurer may require.
The duty payable upon a conveyance to which this section applies will be as follows:
where the amount by reference to which the duty would, apart from this section, be calculated does not exceed the value of the undertaking referred to in subsection (1)(b)—the duty will be $1 000;
where the amount by reference to which the duty would, apart from this section, be calculated exceeds the value of the undertaking referred to in subsection (1)(b)—the duty will be an amount calculated in accordance with the following formula:
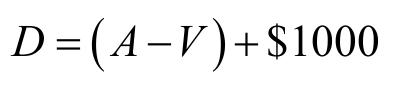
where
D is the amount payable
A is the amount of duty payable apart from this section
V is the amount of duty payable on a conveyance of an interest in property the value of which equals the value of the undertaking referred to in subsection (1)(b).
In this section—
exploration tenement means—
an exploration licence granted under the Mining
Act 1971;
or
an exploration licence granted under the Petroleum and Geothermal Energy Act 2000;
or
an exploration permit for petroleum granted under the Petroleum (Submerged Lands) Act 1982;
or
an exploration licence granted under the Offshore
Minerals Act 2000;
prescribed tenement means—
an exploration tenement; or
a retention tenement;
retention tenement means—
a retention lease under the Mining
Act 1971;
or
a retention licence under the Petroleum and Geothermal Energy Act 2000;
or
a retention lease under the Petroleum (Submerged Lands) Act 1982;
or
a retention licence under the Offshore
Minerals Act 2000.
A reference in this section to a prescribed tenement includes a reference to a portion of a prescribed tenement.
For the purposes of this section, the value of the undertaking referred to in subsection (1)(b) will be taken to be equal to the costs for which the person or persons acquiring an interest in the tenement by virtue of the conveyance become liable, or for which that person or those persons are reasonably expected to become liable, by virtue of the undertaking (assessed as at the time that the undertaking was given).
This section applies to a conveyance first lodged with the Commissioner for stamping on or after the commencement of the Stamp
Duties (Concessional Duty and Exemptions) Amendment Act 1991.
The statute text is free to read above. View subscription options to unlock the case-law research tools for each provision.